The short version
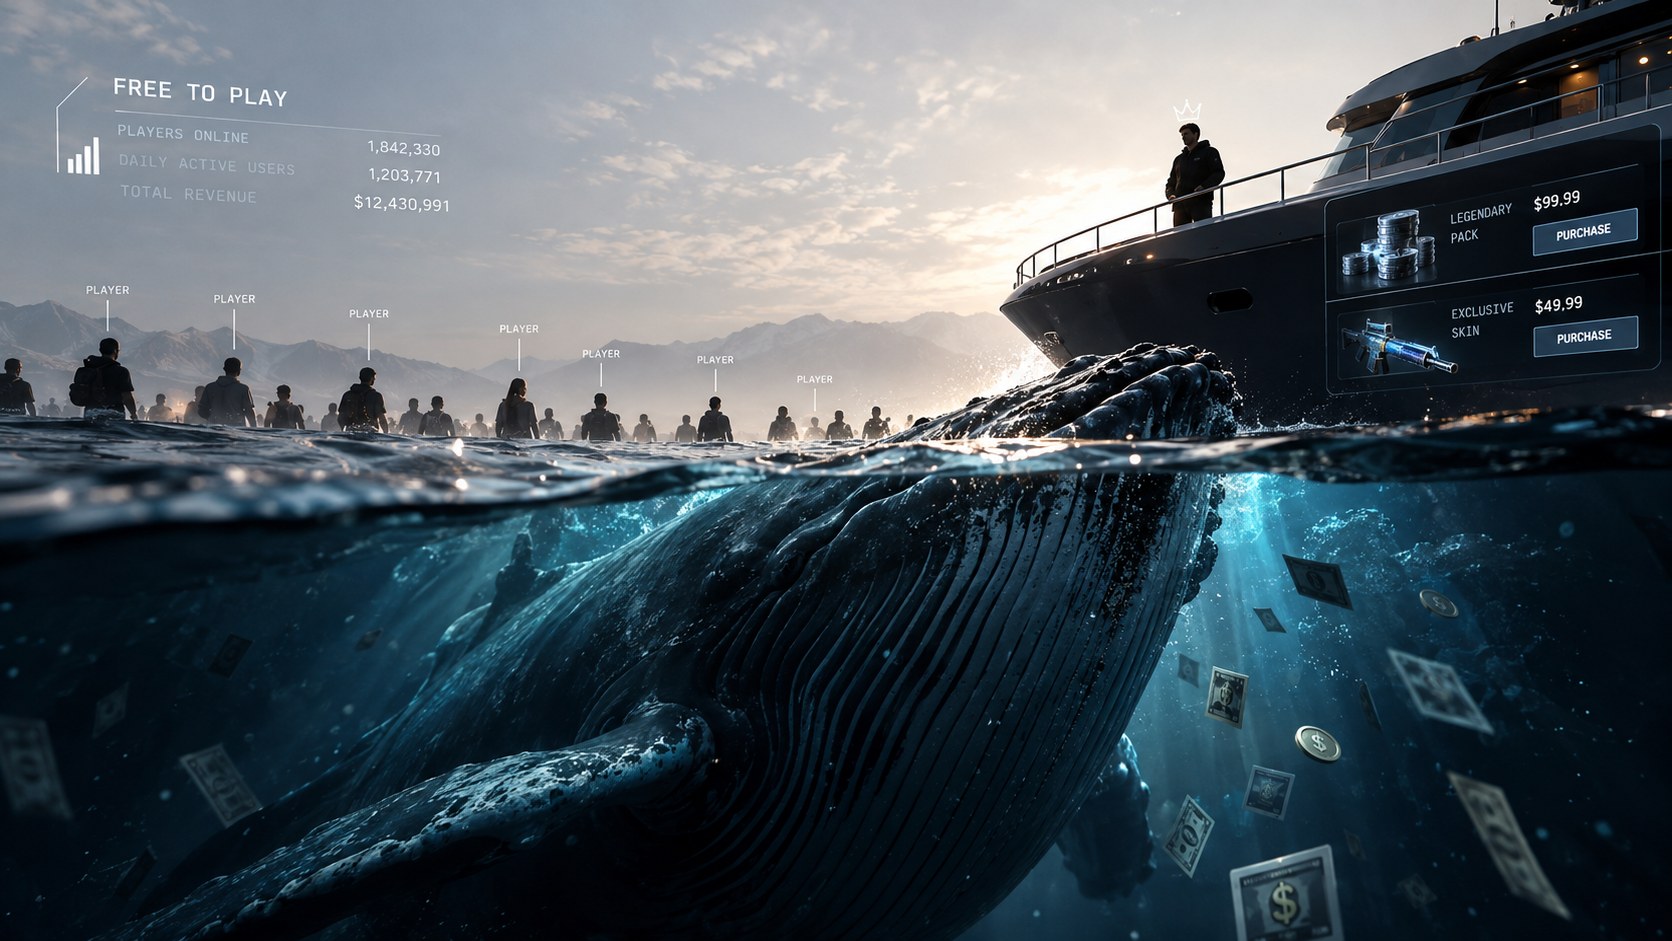
- A “whale” is a high-spending player, but there is no universal dollar threshold; researchers and companies define the group differently.
- Whales matter because free-to-play games can have extremely uneven spending distributions: in some titles, a tiny fraction of payers generates a huge share of in-app-purchase revenue.
- The effect is not universal. Large-scale research finds some mobile games have relatively even payer spending, while others are explicitly whale-driven or primarily monetize through advertising.
- When high spenders carry the economics, their retention and purchase behaviour can influence pricing, live events, progression systems and the kinds of offers a game keeps producing.
- Heavy spending is not proof that a player is wealthy or financially comfortable, which is why whale-dependent design also raises consumer-protection questions.
A free game can still have a very expensive customer
A boxed game gives its publisher a fairly obvious ceiling: sell one copy, collect roughly one purchase price.
Free-to-play breaks that symmetry.
One player can install the game, play for two years and spend nothing. Another can buy a starter pack. Another can spend every week on currency, characters, cosmetics, energy, event entries or progression. There is no requirement that two players contribute anything close to the same amount.
At the far end of that distribution are the players the games business has long called whales.
The term is borrowed from gambling and casino language, and it is not especially elegant. But the economic idea matters: a small number of very high spenders can be worth an enormous amount of revenue to a free-to-play game.
In some games, they matter so much that understanding the business without them is almost impossible.
In others, they barely matter at all.
That distinction is the interesting part.
“Whale” does not have one official definition
There is no universal amount of money that turns a player into a whale.
One company may define whales as its top 5% of paying users. A research paper may study the top 1%. Another study may use a monthly spending threshold. Those definitions can describe very different people.
Moloco’s 2026 analysis of 55 new mobile-game launches, for example, defines a whale as a player in the top 5% of payers by first-year spending for a given game. Academic work has often examined the top 1% or top 10% instead.
That means “5% of payers” should not be casually rewritten as “5% of players.”
The distinction can be huge. AppsFlyer’s 2024 gaming report found that fewer than 5% of users in its sample made an in-app purchase at all. In a game with a similarly low conversion rate, the top 5% of payers would represent only a sliver of the full player population.
So the clean definition is relative:
A whale is a player whose spending sits near the extreme high end of that game’s spending distribution.
The label describes spending. It does not tell you why the person spent, whether they could afford it or whether the game depends on players like them.
The revenue can be dramatically concentrated
The strongest evidence for whale economics is not a story about one person spending $10,000. It is the shape of the entire revenue curve.
A 2023 study in ACM Games: Research and Practice examined $4.7 billion in in-app spending across 2,873 mobile games and more than 69 million players. Instead of finding one universal free-to-play pattern, the researchers found several.
At one end were relatively uniform games, where spending among payers was comparatively even. At the other were hyper-Pareto games, where revenue was heavily concentrated at the top.
In the hyper-Pareto group, the top 1% of spenders generated about 38.8% of revenue. Those games were only 11.8% of the titles in the dataset, but they generated 41.8% of the observed revenue.
The same research found a larger “quasi-Pareto” group where the top 20% of spenders generated about 79% of spending.
That is why the usual claim that “1% of players fund every free game” is too neat. The real distributions vary sharply from game to game.
But the underlying phenomenon is real: some free-to-play businesses are built around an unusually valuable upper tail of spenders.
Whales can become more important as a game ages
The whale effect is not necessarily obvious in launch week.
Moloco followed 55 U.S. mobile-game launches released from January 2024 through September 2025 across their first year. It separated them into three monetization types:
| Model | What primarily makes the money |
|---|---|
| Whale-driven | A small group of high spenders |
| Volume-driven | A broader base of repeat purchasers |
| Ad-driven | Advertising, with thinner in-app-purchase spending |
For its whale-driven games, Moloco classified titles as having more than 70% “whale concentration,” using the top 5% of payers as the whale group.
More interestingly, the concentration increased over time. By month 10, the top 5% of payers generated 81% of monthly in-app-purchase revenue in whale-driven titles and 54% in volume-driven titles.
Most eventual whales were not even present in the first launch month. Their value accumulated as they kept buying.
That makes a whale economically different from someone who buys one $4.99 pack.
The valuable part is often not one spectacular purchase. It is repeat spending over a long player lifetime.
Why one high spender can matter so much
Imagine a game with 100,000 active players.
Suppose 4,000 of them have ever paid. The top 5% of those payers is just 200 people.
If the game’s revenue distribution is heavily concentrated, those 200 customers can matter more to in-app-purchase revenue than tens of thousands of people who enjoy the same game for free.
That changes the economics in three ways.
First, the spending ceiling is high. A $60 game usually sells one $60 copy to a customer. A free-to-play economy can sell the same customer something again tomorrow, next week and next season.
Second, retention becomes revenue. Keeping a high-value payer engaged for another six months may be materially more valuable than converting a large number of players into one-time low spenders.
Third, lifetime value becomes uneven. Two players who look identical in an install report can end up worth radically different amounts.
That is why mobile-game acquisition systems try to predict value rather than simply count installs. Moloco’s 2026 report explicitly argues that eventual top spenders can take months to fully reveal their value.
For a whale-driven game, acquiring the right player can be worth far more than acquiring many average ones.
Whales can influence what the game becomes
Once revenue is concentrated, design and monetization stop being separate subjects.
A game that earns most of its money from repeat high spenders has a strong reason to keep giving those spenders things worth buying.
That can mean deeper progression, recurring events, premium currencies, expensive bundles, collectible characters, cosmetic status goods or competitive advantages depending on the title. The specific mechanic varies. The economic requirement does not: there needs to be enough continuing value for a highly engaged player to purchase again.
Research on 519 free-to-play purchasers found six broad reasons people bought in-game content, including unobstructed play, social interaction, competition and unlocking content. Spending was positively associated with motivations around unobstructed play, social interaction and perceived economic rationale. The design of the game helps create the reason to buy.
This does not mean every feature in a whale-driven game exists to extract money from whales.
It means the revenue model creates an incentive.
If a small group of players produces most of the income, the needs, habits and limits of that group become commercially important. Live-ops teams notice what they buy, what makes them stay and what makes them leave.
The business starts listening very closely to a very small audience.
Free players still matter
The phrase “whales fund everyone else” contains some truth, but it can also make non-spenders sound useless.
They are not.
Free players make matchmaking faster. They populate guilds, leaderboards and social spaces. They create opponents, teammates, viewers, word of mouth and cultural relevance. In ad-supported games, they can also generate revenue without buying anything.
The market is increasingly mixing these systems. Moloco found that 58% of new in-app-purchase launches in its Sensor Tower analysis also used in-app advertising to monetize players who never purchased. AppsFlyer likewise documented a broader move toward hybrid IAP-plus-ad monetization.
A healthy free-to-play economy can therefore involve several groups doing different jobs:
- high spenders generate disproportionate purchase revenue;
- moderate spenders provide recurring volume;
- non-spenders create audience, activity and sometimes advertising revenue.
The whale may carry the revenue curve. The whale still needs a game worth being inside.
Not every successful free-to-play game needs whales
This is the part that gets lost whenever free-to-play is described as one giant whale-hunting machine.
The 2023 ACM dataset found that 34.4% of the games it studied fell into its most uniform spending cluster. Their top 1% of spenders generated only about 5% of revenue.
Moloco’s newer launch data also separates ad-driven games from whale- and volume-driven ones.
And there are famous counterexamples.
When Crossy Road launched in 2014, developer Hipster Whale deliberately tried to monetize broadly rather than build a system where a tiny percentage of players carried the business. Co-creator Andrew Sum told Game Developer that the team wanted the game to appeal to everyone and used optional video ads as a major revenue source. The game made more than $1 million from video ads in its first month.
Free-to-play describes the entry price.
It does not prescribe one revenue distribution.
The uncomfortable part: “whale” does not mean “rich”
A high spender is not automatically a wealthy person casually burning disposable income.
That assumption matters because it changes how whale-dependent design should be judged.
A 2026 Frontiers in Public Health study of Austrian adolescents found that the top 10% of past-year in-game spenders in its payer subsample accounted for 61.4% of total spending. Heavy spenders also showed higher rates of gaming- and gambling-disorder measures. Family affluence was not significantly associated with spending levels in that sample.
The study is about adolescents, so it should not be generalized to every adult free-to-play player. But it makes one point clearly: high spending cannot simply be assumed to mean high financial capacity.
Loot-box research points in a similar direction. A 2021 secondary analysis of 7,767 loot-box purchasers found that the top 5% of spenders accounted for half of the observed loot-box revenue, while self-reported spending had no significant correlation with self-reported earnings.
Loot boxes are only one monetization mechanic, and a loot-box purchaser is not the same thing as every free-to-play whale. The useful lesson is narrower:
Revenue concentration tells you who spent the most. It does not tell you who could most comfortably afford to.
That is where the business logic collides with consumer protection.
Whale economics are powerful because the average hides the game
An average revenue-per-player number can make a free-to-play economy look ordinary.
The average is often the wrong place to look.
One player spends nothing. Another spends $2. Another buys every battle pass. Another becomes one of the top 1% and spends hundreds or thousands across the life of the game.
Put them together and the mean smooths away the exact behaviour that may be driving the business.
Whales matter because free-to-play allows extreme differences in customer value. In the games where that distribution becomes highly concentrated, a tiny group can finance a disproportionate share of development, live operations and user acquisition — and can therefore influence what the game is optimized to sell and retain.
But “free-to-play” is not synonymous with “whale-driven.”
Some games spread spending widely. Some monetize mainly through ads. Some mix subscriptions, battle passes, purchases and advertising. Some genuinely depend on a small number of very high spenders.
The useful question is not whether a free game has whales.
It is:
How much of the game’s economy depends on them?
Sources & reference material
- The Many Faces of Monetisation: Understanding the Diversity and Extremity of Player Spending in Mobile Games via Massive-scale Transactional AnalysisACM Games: Research and Practice · Accessed Oct 10, 2026
Large-scale analysis of $4.7 billion in in-app spending across 2,873 mobile games and more than 69 million players, documenting sharply different revenue distributions and a hyper-Pareto cluster in which the top 1% of spenders generated about 38.8% of revenue.
- Inside a mobile game’s first yearMoloco · Accessed Oct 10, 2026
Analysis of 55 U.S. mobile-game launches released from January 2024 to September 2025, including whale-, volume- and ad-driven monetization archetypes and the growing revenue share of the top 5% of payers over a launch year.
- The State of Gaming App Marketing — 2024 EditionAppsFlyer · Accessed Oct 10, 2026
Aggregated mobile-gaming benchmark showing that fewer than 5% of users made an in-app purchase in the report sample and documenting the industry shift toward hybrid in-app-purchase and advertising models.
- Why do players buy in-game content? An empirical study on concrete purchase motivationsComputers in Human Behavior · Accessed Oct 10, 2026
Survey of 519 free-to-play purchasers finding that unobstructed play, social interaction and economic rationale were positively associated with spending, after purchase motivations were developed from research, industry input and analysis of top-grossing games.
- Heavy spenders in digital games: expenditure disparities and associations between microtransactions, gaming disorder and gambling disorder among adolescentsFrontiers in Public Health · Accessed Oct 10, 2026
Study of Austrian adolescents finding that the top 10% of past-year in-game spenders accounted for 61.4% of spending in the payer subsample, with heavy spending associated with higher gaming- and gambling-disorder measures and not significantly associated with family affluence.
- Secondary analysis of loot box data: Are high-spending “whales” wealthy gamers or problem gamblers?Addictive Behaviors · Accessed Oct 10, 2026
Secondary analysis of 7,767 loot-box purchasers finding that the top 5% of spenders accounted for half of loot-box revenue and that self-reported spending was not significantly correlated with self-reported earnings.
- How Crossy Road made $1 million from video adsGame Developer · Accessed Oct 10, 2026
Developer interview documenting Crossy Road’s deliberate choice to monetize broadly with optional video advertising rather than build around a small group of high spenders.